Correction, 9/24/2026. Sentences in this report paired a direction word with a figure of the opposite sign -- describing a decline as a gain, or a gain as a drop. The figures were correct and match the tables below; the wording was not, and has been fixed. No figure has changed.
Correction, 9/21/2026. The percentage moves in this report were measured from each session's opening price to its close, not from the previous session's close, which is how a daily change is normally stated. The figures in the text are those open-to-close moves. The tables now label them as such and add each name's daily change against the prior close. Measured against the prior close, 15 of the 19 names in the tables moved in the opposite direction from the one given in the text: XLE (printed +0.63%, daily change -3.48%); XOP (printed +0.53%, daily change -4.22%); ICLN (printed -1.08%, daily change +0.53%); XOM (printed +0.84%, daily change -4.14%); CVX (printed +0.84%, daily change -3.64%); COP (printed +1.02%, daily change -4.03%); OXY (printed +1.89%, daily change -3.68%); BP (printed +1.41%, daily change -2.78%); SHEL (printed +0.89%, daily change -3.56%); FCX (printed -1.49%, daily change +2.51%); SCCO (printed -3.39%, daily change +1.81%); NEM (printed -1.12%, daily change +5.56%); B (printed -0.88%, daily change +4.05%); AEM (printed -0.85%, daily change +5.63%); MP (printed -3.00%, daily change +1.23%). Closing prices are unaffected and were correct as published.
Market Overview
Energy markets demonstrated clear sectoral rotation Tuesday as uranium and specialty materials significantly outperformed traditional hydrocarbon equities. Cameco (CCJ) led the session with a gain of +1.92%, while Southern Copper (SCCO) fell -3.39%, underscoring the divergent forces at work across the energy landscape. The broader Energy Select Sector SPDR (XLE) posted +0.63%, reflecting mixed sentiment toward conventional energy plays even as alternative energy subsectors attracted renewed investor interest.
Oil & Gas Sector Under Pressure
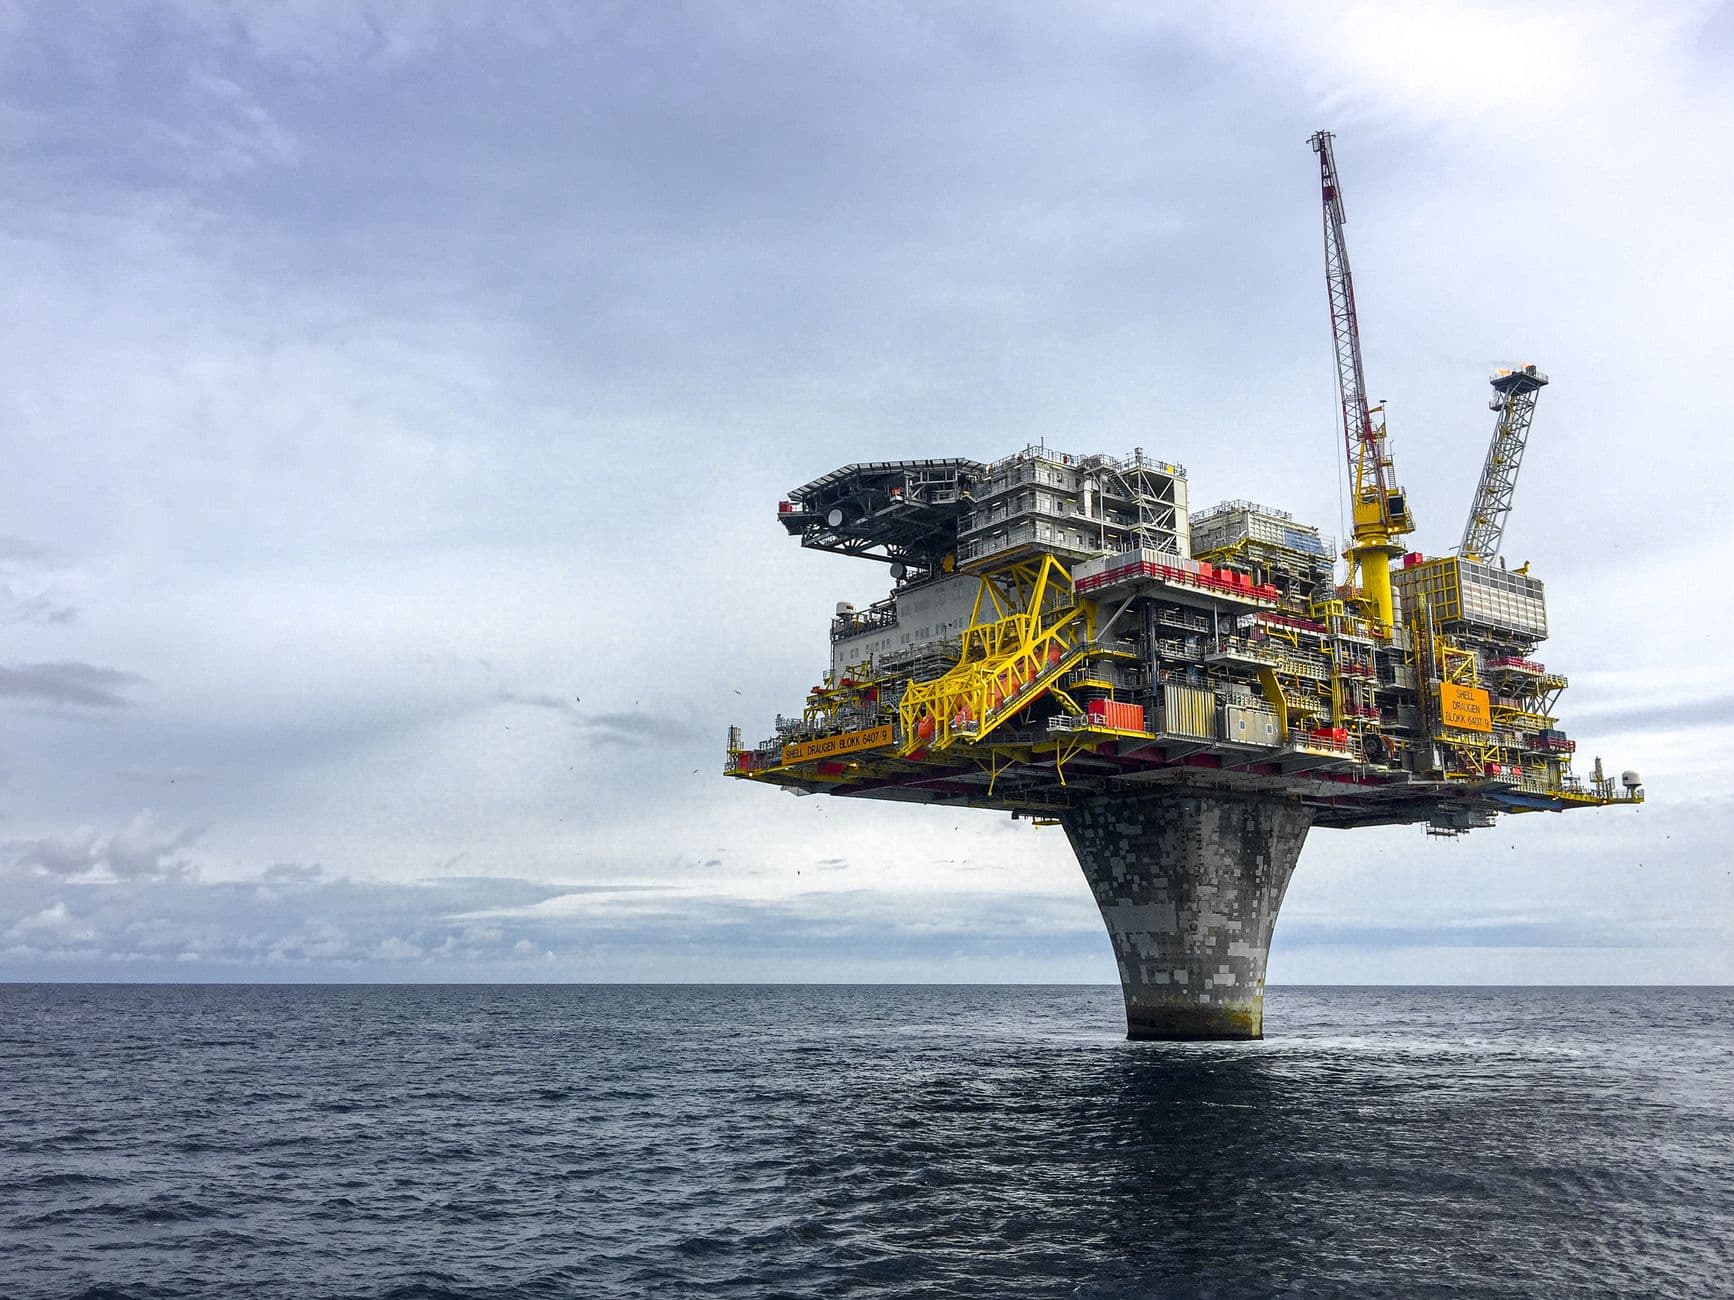
The integrated majors faced headwinds throughout the session. ExxonMobil (XOM) rose +0.84% to close at $140.92, while Chevron (CVX) gained +0.84% to $180.40. Shell plc (SHEL) similarly firmed, climbing +0.89% to $82.61, and BP plc (BP) added +1.41% to finish at $41.59. This broad-based weakness among the supermajors suggests concerns about near-term crude demand or margin compression may be weighing on investor sentiment.
The exploration and production space fared little better, with SPDR S&P Oil & Gas Exploration (XOP) advancing 0.53%. Independent producers showed varied performance, though the overall trend tilted negative. ConocoPhillips (COP) rose +1.02% to $112.26, while Occidental Petroleum (OXY) gained +1.89% to reach $54.46. The softness in upstream equities despite relatively stable fundamentals points to possible position adjustments ahead of mid-quarter reporting or technical profit-taking following recent strength.
Metals & Mining Mixed Across Subsectors
Base and precious metals showed notable divergence. Copper-focused equities demonstrated relative strength, with Freeport-McMoRan (FCX) declining -1.49% to $70.13 and Southern Copper (SCCO) falling -3.39% to $193.22. The industrial metal complex appears to be benefiting from infrastructure investment narratives and supply constraint concerns, even as broader commodity markets remain choppy.
Precious metals miners delivered a mixed performance despite gold trading at $4,315.14, showing +0.50% on the session. Newmont (NEM) lost -1.12% to close at $105.80, while Agnico Eagle Mines (AEM) shed -0.85% to reach $171.80. Gold itself moved +0.50%, while silver finished at $69.91, registering -0.55%. The divergence between gold price action and miner performance suggests equity investors remain cautious about cost structures and operational execution despite supportive metal prices.