Correction, 9/24/2026. Sentences in this report paired a direction word with a figure of the opposite sign -- describing a decline as a gain, or a gain as a drop. The figures were correct and match the tables below; the wording was not, and has been fixed. No figure has changed.
Correction, 9/21/2026. The percentage moves in this report were measured from each session's opening price to its close, not from the previous session's close, which is how a daily change is normally stated. The figures in the text are those open-to-close moves. The tables now label them as such and add each name's daily change against the prior close. Measured against the prior close, 4 of the 19 names in the tables moved in the opposite direction from the one given in the text: TAN (printed -0.13%, daily change +1.22%); ICLN (printed -0.88%, daily change +0.05%); SHEL (printed -0.79%, daily change +0.27%); NEM (printed -0.23%, daily change +0.49%). Closing prices are unaffected and were correct as published.
The energy complex closed Wednesday's session in a rare moment of unified weakness, with traditional oil and gas, uranium, renewables, and base metals all retreating as investors rotated toward safe-haven assets. Energy Select Sector SPDR (XLE) declined -0.77%, marking a sharp reversal from recent sessions that saw subsector divergence dominate trading patterns.
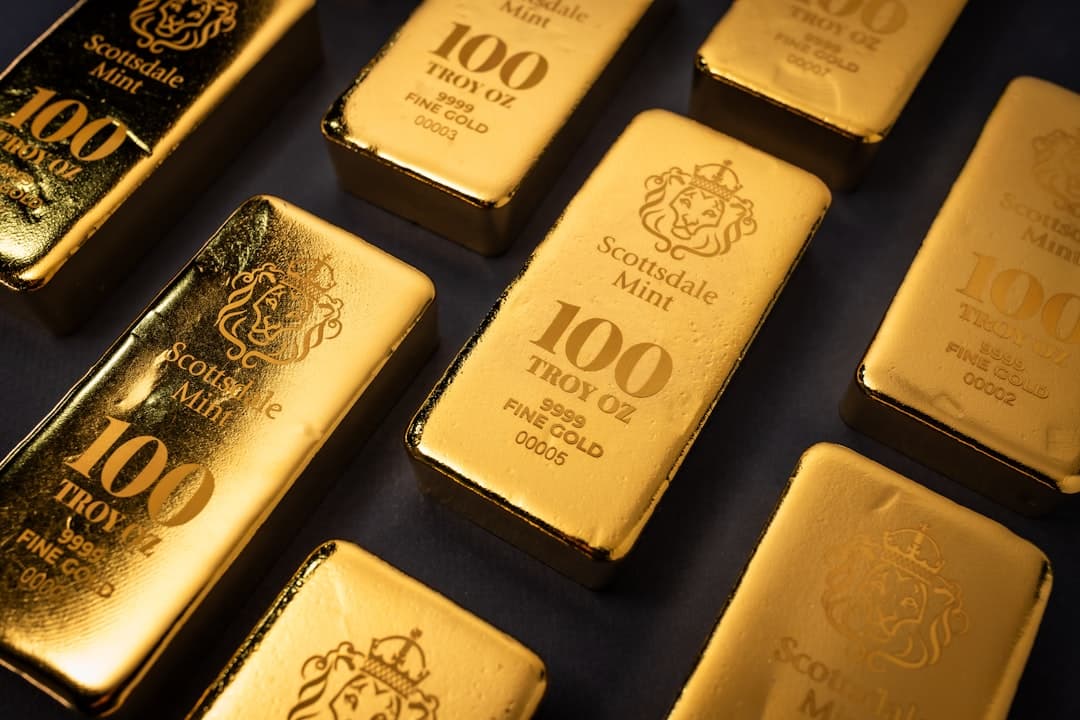
The session's most striking feature was the breadth of selling pressure across energy-related equities even as gold advanced +0.10% to close at $4,057.43, signaling a flight to safety that left commodity-linked stocks behind. MP Materials (MP) led decliners, falling -2.95%, while Invesco Solar ETF (TAN) held up best, slipping just 0.13% from its open and finishing 1.22% above the prior close.
Oil and Gas Majors Retreat in Lockstep
The traditional energy sector saw coordinated weakness across both U.S. supermajors and European integrated producers. ExxonMobil (XOM) declined -0.40% to $144.51, while Chevron (CVX) slipped -0.31% to $181.60. The exploration and production segment fared no better, with SPDR S&P Oil & Gas Exploration (XOP) falling -0.61% as smaller producers tracked the majors lower.
ConocoPhillips (COP) retreated -0.50%, and Occidental Petroleum (OXY) declined -1.45%, continuing the broad-based pressure across the domestic production landscape. European majors mirrored the weakness, with BP plc (BP) falling -0.53% and Shell plc (SHEL) declining -0.79%, eliminating any geographic divergence that has characterized recent sessions.
The uniformity of losses across the oil and gas complex suggests macro headwinds rather than company-specific concerns drove Wednesday's action, with the sector moving in tandem regardless of operational profile or regional exposure.
Mining Sector Joins the Decline
Base and precious metals miners closed lower despite gold's advance, highlighting the session's risk-averse character. Copper producers led the mining retreat, with Freeport-McMoRan (FCX) falling -2.65% and Southern Copper (SCCO) declining -1.55%. The weakness in copper-focused equities came even as industrial metals have recently shown resilience on infrastructure demand expectations.
Gold miners failed to capitalize on the yellow metal's rally, with Newmont (NEM) slipping -0.23%, Barrick Mining (B) declining -1.75%, and Agnico Eagle Mines (AEM) retreating -1.50%. The disconnect between physical gold strength and equity weakness suggests investors favored direct commodity exposure over mining company leverage, potentially reflecting concerns about operational costs or margin compression.
Rare earth and critical minerals specialist MP Materials (MP) declined -2.95%, extending losses across the specialty metals segment.