Wednesday, November 4, 2026Vol. III · No. 308Subscribe
The Mining, Energy & Technology Wire

Mining Press Roundup: Ivanhoe Trims Kamoa-Kakula Again as Freeport Commits to Bagdad

Ivanhoe Mines cut its Kamoa-Kakula forecast for a second time while Freeport approved a major Bagdad expansion, and Chile's copper outlook weakened further.

Mining Press Roundup: Ivanhoe Trims Kamoa-Kakula Again as Freeport Commits to Bagdad
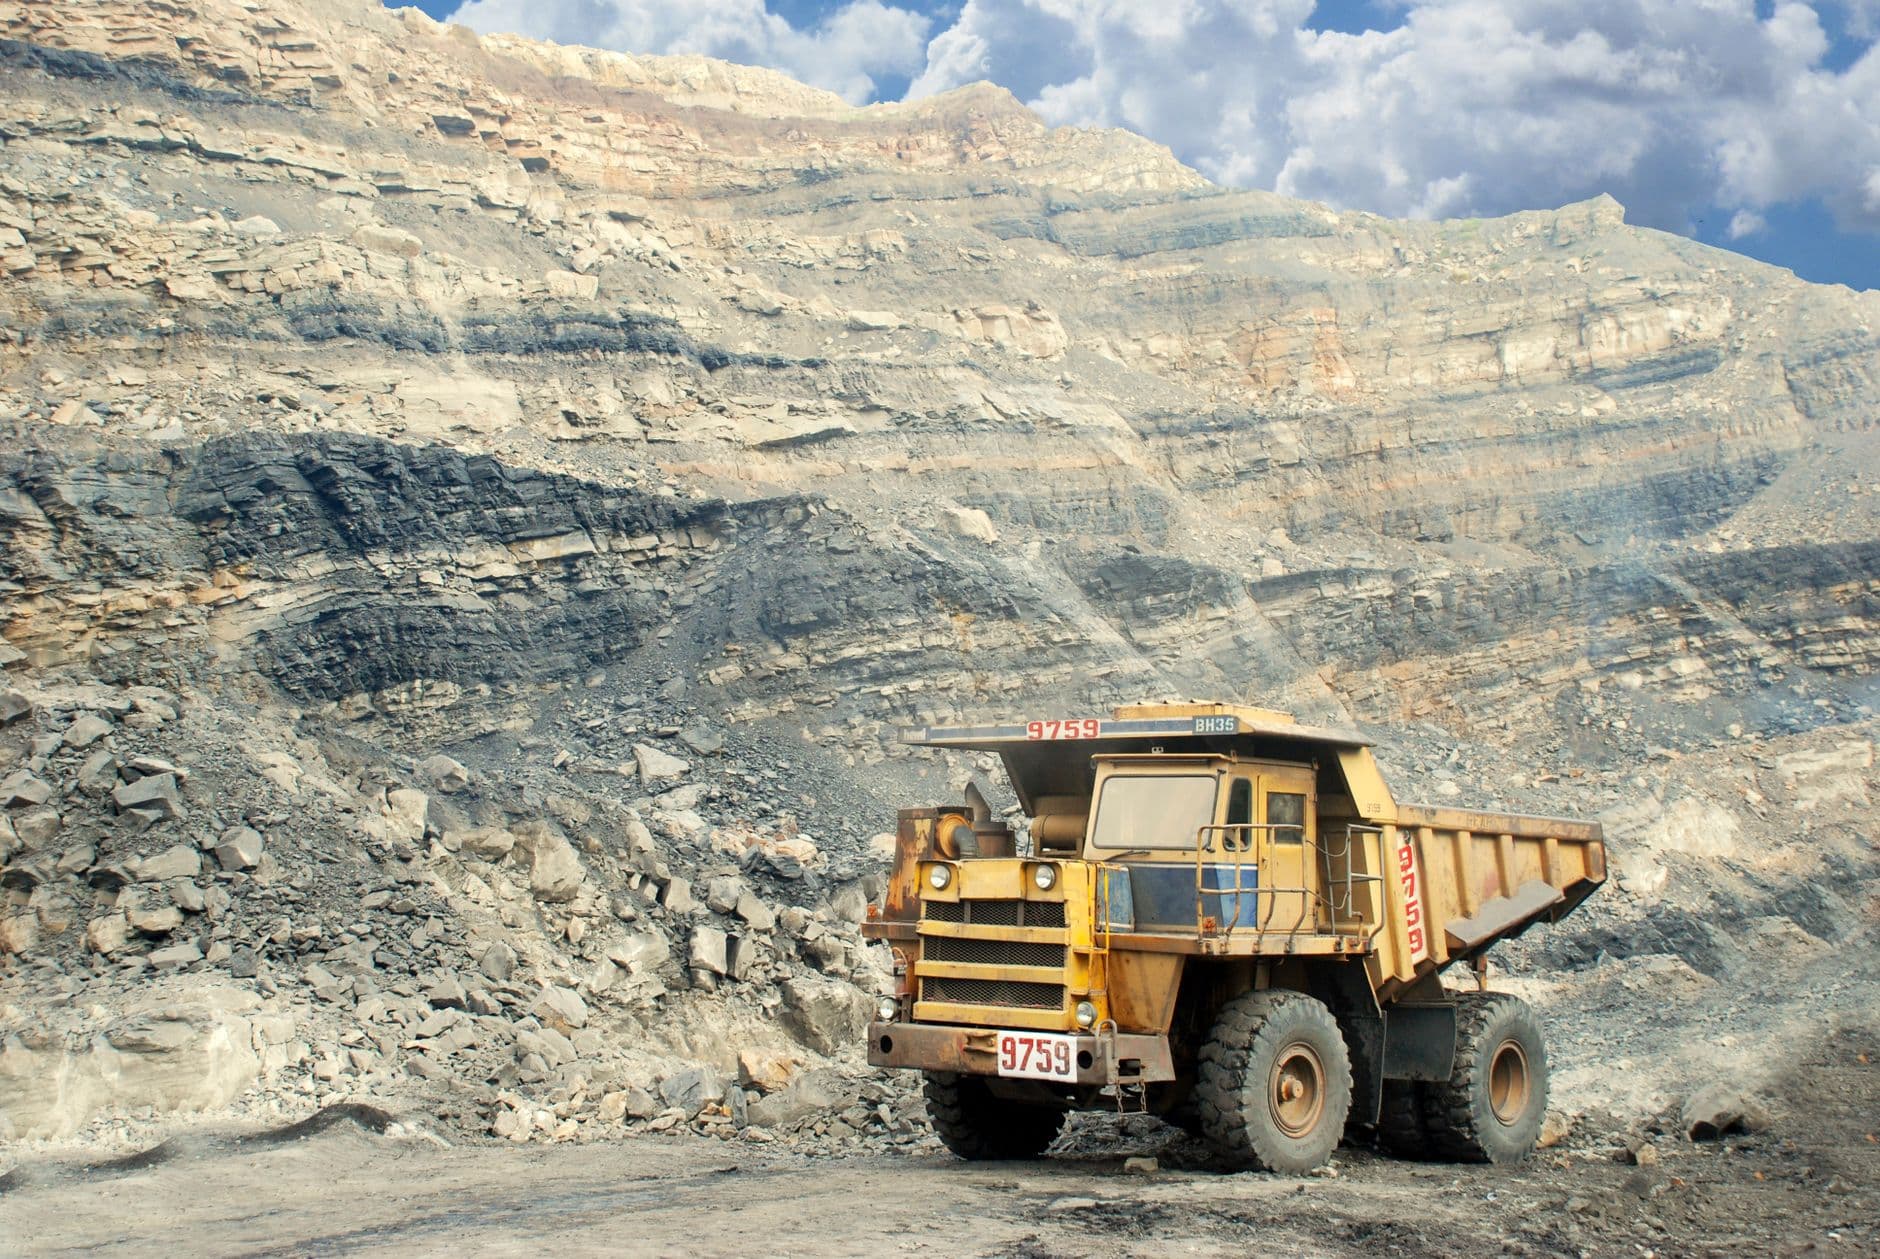
PhotographIvanhoe Mines cut its Kamoa-Kakula forecast for a second time while Freeport approved a major Bagdad expansion, and Chile's copper outlook weakened further.Photo: Enrique / Pexels

Ivanhoe Mines has cut its 2027 copper production forecast for Kamoa-Kakula in the Democratic Republic of Congo for the second time this year, MINING.COM reported. Freeport announced on November 4, 2026 that its board had approved a $4.5 billion expansion and modernization program at Bagdad in Arizona. The two announcements show how hard new copper supply is to deliver, whether the project is a deep underground ramp-up in Central Africa or a brownfield rebuild in the American Southwest. They also land as Chile's output estimates keep falling and a changed Congress takes shape in Washington.

Ivanhoe Mines: Kamoa-Kakula Guidance Cut Again

Ivanhoe now expects Kamoa-Kakula to produce 300,000 to 350,000 tonnes of copper next year, down from 380,000 to 420,000 tonnes, according to MINING.COM. The 2027 target stood at 500,000 to 540,000 tonnes before a more cautious mine plan emerged in March. Ivanhoe also lowered the expected steady-state annual capacity of the existing Phase 1, 2 and 3 concentrators to 400,000 to 450,000 tonnes as it prepares to add shallow open-pit mining.

Costs are moving the wrong way too. Ivanhoe raised its 2027 cash cost (C1) guidance to $2.50 to $3.00 per pound from $2.10 to $2.50, citing prolonged high diesel prices, lower ore grades and reduced production. Production mining on the eastern side of Kakula is now expected to restart in late March 2028, rather than late 2027, following further geological and engineering work.

The near term is steadier. Kamoa-Kakula produced 76,401 tonnes of copper in saleable products in the third quarter, up from 64,328 tonnes in the preceding three months. Full-year 2026 output is expected to reach approximately 290,000 tonnes. Ivanhoe plans to begin detailed engineering for a Phase 4 concentrator expansion in the first quarter of 2027, but that expansion has not yet received project approval.

The market reaction was sharp. TD Cowen analyst Craig Hutchison downgraded Ivanhoe to hold from buy and cut his target price to C$9 ($6.42) from C$14. "The path back to about 500,000 tonnes per year has become longer, more capital intensive and more dependent on future execution." he wrote.

Freeport: $4.5 billion for Bagdad

Freeport (NYSE:FCX) said the Bagdad program for its wholly owned copper and molybdenum operation in northwest Arizona would increase annual long-term copper production to over 400 million pounds. That includes incremental production of approximately 225 million pounds per annum. Molybdenum production would rise to over 20 million pounds per annum, an incremental 12 million pounds per annum.

The construction period is approximately 3.5 years, with initial production targeted in mid-2030. Freeport says project break-even economics are supported at a copper price of approximately $4.00 per pound ($20 per pound molybdenum). Approximately 20% of project costs are expected to be funded in 2027, 30-35% in 2028 and the balance in 2029-2030. Bagdad reserves are 2.6 billion metric tons of ore with copper equivalent grade of 0.43%, per the company.

CEO Kathleen Quirk said the expansion is "an important step in advancing Freeport's U.S. copper growth strategy."

The price tag is higher than earlier estimates. MINING.COM reports Bagdad's capital costs are about $1 billion, or 29%, above the $3.5 billion estimate prepared in 2023. BMO Capital Markets analyst Katja Jancic said the approval was "largely anticipated" and that capital intensity, production expectations and timing were consistent with prior communications.

Cochilco: Chile's Copper Outlook Slides

Cochilco, Chile's copper commission, now expects Chilean output to fall 8.4% in 2026, compared with the 2.6% decline projected in August. Chile is expected to produce 4.94 million tonnes of copper this year and 5.08 million tonnes next year, down from Cochilco's August forecasts of 5.27 million and 5.55 million tonnes.

BMO Capital Markets analysts Helen Amos and George Heppel said the downgrade could leave Chile with its weakest annual copper production in more than two decades. Cochilco still raised its average copper price forecast for 2027 by 17% to $5.95 per lb. from $5.10. It forecasts a refined-copper surplus of 144,000 tonnes this year, widening to 215,000 tonnes next year, or 0.8%.

The metal itself was under pressure. Copper fell 2.1% to $14,034 a tonne on the London Metal Exchange on Tuesday, its lowest level since mid-August, as uncertainty over the US midterm elections weighed on metals. The COPX copper miners ETF closed at $71.71, down 1.6% on the day, according to market data.
Capitol Hill: Midterms Reset the Policy Backdrop

Democrats won control of the House of Representatives and Senate in Tuesday's midterm elections, setting up divided government from January, MINING.COM reported. In August, Senator Martin Heinrich and Representative Jared Huffman sought a Government Accountability Office investigation into financial safeguards and potential conflicts when Washington acts as both investor and regulator in mining companies.

Trade policy stays with the White House. BMO said Section 232 duties on steel, aluminum and copper products remain under presidential authority, as would potential tariffs on refined copper from January. The Senate has scheduled a procedural vote for Nov. 9 on advancing the legislation serving as the vehicle for permitting reform.

The import numbers show why this matters. Net imports supplied 57% of US refined-copper consumption in 2025, according to US Geological Survey data cited by MINING.COM. MINING.COM also reports the White House points to China's control of global copper smelting capacity.

Rare Earths Norway: Fen Pilot Plant Approved

Rare Earths Norway, a privately held developer, approved construction of a €24-million ($27 million) pilot plant to test processing of material from its Fen project. The plant in Ulefoss is scheduled to start operating in the third quarter of 2027. Funding includes €5.4 million from Innovation Norway and €1.9 million from the Telemark Development Fund.

A March resource update for Fen outlined 123 million indicated tonnes grading 1.35% total rare earth oxides, and inferred resources of 1.08 billion tonnes grading 1.31%. CEO Håvard Moe said: "This investment is a concrete step towards bringing the Fen deposit into production."

Standard Lithium: Eyeing a Year-End Decision

Standard Lithium is targeting a year-end investment decision on its $1.45-billion capex South West Arkansas project in the Smackover Formation. Smackover Lithium has offtake deals covering up to 20,000 tonnes of lithium carbonate annually, or about 89% of the project's planned output. The LIT lithium ETF closed at $60.10, up 0.1%, according to market data.

MetalMiner: Tungsten's Price Gap Widens

Rotterdam ammonium paratungstate (APT) traded at $278.22 per kg in October, compared with $74.43 per kg for China ex-works APT, a 3.74-fold difference, according to a MetalMiner report. The Rotterdam-to-China multiple averaged 1.24 times from September 2021 to June 2025.

US tariffs on tungsten rose from about 4% (2015 to 2024) to 16.2% in December 2025, per the same report. A Defense Federal Acquisition Regulation Supplement (DFARS) procurement restriction on the origin of tungsten used in the US is set to take effect on January 1, 2027.

What It Means

The day's clearest theme is that supply growth is arriving later and at higher cost than plans promised. Ivanhoe has cut its guidance again and pushed back its eastern Kakula restart. Chile's forecasts keep falling. Freeport's Bagdad, even with capital costs above the 2023 estimate, will not produce until mid-2030. Cochilco's higher 2027 price forecast sits alongside a projected refined surplus, so the market is not uniformly tight. The difficulty of delivering new tonnes is the common thread.

The policy picture is less settled. A divided Congress from January, a pending permitting vote and presidential control over tariffs leave US supply-security policy open, just as the import-dependence figures and the tungsten sourcing rules draw more attention to it.


This roundup covers press releases published on November 4, 2026. Company announcements are sourced from mining industry wire services. For corrections or updates, contact contact@stakeandpaper.com.

Original reporting and analysis by the Stake & Paper editorial team. See linked sources within the article.

Share this story

More from Stake & Paper

Was this article helpful?

ClaimWatch

Mining claims intelligence — from query to report, in minutes.

Every unpatented mining claim across all twelve BLM states. Leadfile audits, due diligence, site selection, regional prospecting, entity investigations, and AOI monitoring — delivered as complete report packages.

4.4M+
Claims Tracked
12
BLM States
7
Report Types
Request a Sample Report
Stake & Paper AM

One morning brief. The whole energy sector.

Original analysis, the day's most important wire stories, and market data — delivered before your first cup of coffee. Free.